Dubai · Investment Guide
Non-residents can obtain a mortgage in Dubai from several UAE banks. The loan-to-value limit is each bank's own policy, typically 50–60% of the property value, so plan for a 40–50% cash deposit plus 6–7% in costs. This guide covers eligibility, rates, documentation, and how to navigate the process from abroad.
Yes. UAE law does not restrict mortgage lending to residents. Several major banks — including Emirates NBD, ADCB, Mashreq, HSBC UAE and ADIB — actively offer mortgage products to non-resident foreign nationals purchasing in Dubai's freehold zones. The key difference versus UAE residents is the loan-to-value limit. The Central Bank's mortgage regulation sets caps for UAE nationals and for resident expatriates (80% on a first home up to AED 5M) and has no non-resident category, so each bank sets its own non-resident limit: ADIB and Mashreq lend up to 50% of the property value, HSBC up to 60%.
In practice, this means a non-resident buying a property at AED 2,000,000 can typically borrow AED 1,000,000–1,200,000 and must provide AED 800,000–1,000,000 (40–50%) as a cash deposit, plus transaction costs (approximately 6–7% of the purchase price).
The Central Bank of the UAE's Regulations Regarding Mortgage Loans set the maximum LTV that licensed banks may lend to UAE nationals and to resident expatriates, by property value and purpose. Off-plan is capped at 50% for everyone. Non-residents are not a category in the regulation, so the rows below for them are each bank's published policy, not a regulatory cap.
| Buyer type | Max LTV | Min deposit | Set by |
|---|---|---|---|
| Resident expatriate, first home up to AED 5M | 80% | 20% of purchase price | Central Bank regulation |
| Resident expatriate, first home above AED 5M | 70% | 30% of purchase price | Central Bank regulation |
| Resident expatriate, second or investment property | 60% | 40% of purchase price | Central Bank regulation |
| Off-plan, any buyer | 50% | 50% of purchase price | Central Bank regulation |
| Non-resident at HSBC | 60% | 40% of property value | Bank policy |
| Non-resident at ADIB, Mashreq, ADCB | 50% | 50% of property value | Bank policy |
Advertised mortgage rates in Dubai start from about 4% per annum in October 2026 (ADCB from 3.99%, HSBC 4.05% fixed, ADIB non-resident finance from 3.99%), with Mashreq's representative one-year fixed rate at 5.00%. What you are offered depends on the bank, the loan term, your profile and whether you choose a fixed or variable rate product.
Fixed-rate mortgages — typically 1, 3, or 5 years fixed, then reverting to a variable rate — give certainty on monthly payments during the fixed period. Variable-rate mortgages are priced at a margin over EIBOR (the Emirates Interbank Offered Rate) and move with market rates: the Central Bank raised its Base Rate from 3.65% to 3.90% on 17 September 2026, and three-month EIBOR rose to about 4.3–4.4% in late September, so variable rates now price off a higher base.
Maximum mortgage terms are typically 25 years for non-residents, and the loan must be repaid by age 65–70 (depending on the bank). For non-residents who are employees, banks will normally lend against income documented in any major currency. For self-employed non-residents, underwriting is more conservative and typically requires 2 years of audited financial statements.
While each bank has slightly different requirements, the standard document pack for a non-resident mortgage application typically includes:
- Valid passport (all pages)
- Last 6 months' personal bank statements (showing salary credits or business income)
- Salary certificate or employment contract (for employed applicants)
- Last 2 years' audited accounts or tax returns (for self-employed applicants)
- Credit report from your home country (some banks require it; others run their own international credit checks)
- Details of the property being purchased (title deed or developer SPA for off-plan)
Applications can usually be submitted to the bank remotely; however, signing the mortgage agreement typically requires the buyer to be present in the UAE or to use a Power of Attorney signed before a UAE-accredited notary in the buyer's home country.
The table below compares the banks most active with non-resident buyers in Dubai's freehold market, using each bank's publicly advertised "from" rate. Unless the row says otherwise, these are resident rates — best-case offers for salary-transfer customers — and non-resident pricing usually carries a premium. Variable rates now price off a higher EIBOR (three-month EIBOR about 4.3–4.4% in late September 2026, after the Central Bank raised its Base Rate to 3.90% on 17 September), so expect a quote above the advertised resident rate and ask for it in writing. Advertised rates last verified in October 2026.
We work with a licensed mortgage broker who submits your application to several of these banks simultaneously and negotiates pricing on your behalf — one document pack, multiple offers, at no cost to you.
| Bank | Advertised rate (p.a.) | What to know as a non-resident |
|---|---|---|
| Emirates NBD | 1-month EIBOR + 1.99% (variable, expatriate home loan) | Dedicated expatriate home-loan product; the UAE's largest bank by assets. The "3.99%" on its page is a tentative figure from November 2024 EIBOR, not a fixed rate |
| HSBC UAE | 4.05% fixed | Non-resident product borrows up to 60% of the property value; an existing HSBC relationship streamlines underwriting |
| ADCB | From 3.99% | Fixed-rate periods of up to 5 years; up to 50% for non-residents |
| Mashreq | 5.00% fixed for 1 year (representative, Key Facts Statement) | No advertised rate on the live page; non-resident FAQ states up to 50% of the property value |
| ADIB | From 3.99% (profit rate, non-resident product) | Islamic home finance for non-residents: up to 50% of the property value, up to AED 5M |
| Dubai Islamic Bank | EIBOR + margin, quote on request | Sharia-compliant home finance — Ijara or Murabaha structure; no advertised rate found |
"Mortgage", "home loan" and "property finance" describe the same thing in Dubai — a bank lending against the property you are buying. What genuinely differs is the structure. Conventional banks charge interest on a loan. Islamic banks such as ADIB and Dubai Islamic Bank cannot, so they use Sharia-compliant alternatives: under Ijara the bank buys the property and leases it to you until the final payment transfers ownership, and under Murabaha it buys and resells to you at an agreed mark-up paid in instalments. The cost is quoted as a profit rate rather than an interest rate, and it is directly comparable — compare total cost over the term, not the label.
One point that catches non-residents out: the Central Bank's 80% cap applies to resident expatriates, and the regulation has no non-resident category at all. Each bank sets its own non-resident limit — ADIB's published non-resident home finance advertises up to 50% of property value, Mashreq's non-resident FAQ says the same, HSBC lends up to 60%. Ask each bank for its non-resident LTV specifically, because the deposit you actually need is 40–50%, not the 20% a resident puts down.
Sharia-compliant finance is open to buyers of any faith, and the same bank LTV policies, DLD fees and mortgage registration fee of 0.25% apply either way.
In addition to the standard DLD transfer fee of 4% of the purchase price, mortgaged buyers pay a mortgage registration fee of 0.25% of the mortgage value, payable to the DLD at the time of transfer, plus AED 250 for the title deed and AED 10 each for the knowledge and innovation fees. The DLD service page states no cap on the 0.25%. The registration trustee (service partner) charges AED 4,000 + VAT for the mortgage registration, or AED 5,000 + VAT for an Oqood (off-plan) mortgage.
For a non-resident buying at AED 2,000,000 with a 50% LTV mortgage (AED 1,000,000 loan):
- DLD transfer fee: AED 80,000 (4%)
- Registration trustee fee for the sale: AED 4,200 (AED 4,000 + 5% VAT)
- Title deed, knowledge and innovation fees: AED 270
- Mortgage registration fee: AED 2,500 (0.25% of AED 1,000,000) + AED 270 fixed fees
- Mortgage registration trustee fee: AED 4,200 (AED 4,000 + 5% VAT)
- Agency commission: approximately AED 40,000 (2%)
Total transaction costs: approximately AED 131,440 — roughly 6.6% of the purchase price. Some banks also charge a processing or arrangement fee (typically AED 2,500–AED 10,000) for the mortgage itself.
For ready (secondary market) properties, a bank mortgage is typically the only structured financing option available. For off-plan properties, developer payment plans are an alternative that requires no bank involvement during the construction period — the buyer pays the developer in stages, and may optionally arrange a bank mortgage at handover to fund the remaining balance.
Developer payment plans on competitive launches often offer 40/60 or even post-handover structures, which can be more flexible than a standard mortgage — especially for buyers who want to spread payments without committing to a long-term loan. The trade-off is that the AED is pegged at 3.67 per USD, so currency risk is minimal for USD-base investors, but buyers earning in weaker currencies should factor in exchange rate movements over a multi-year payment period.
Available Now
Curated by our investment team. Updated weekly.
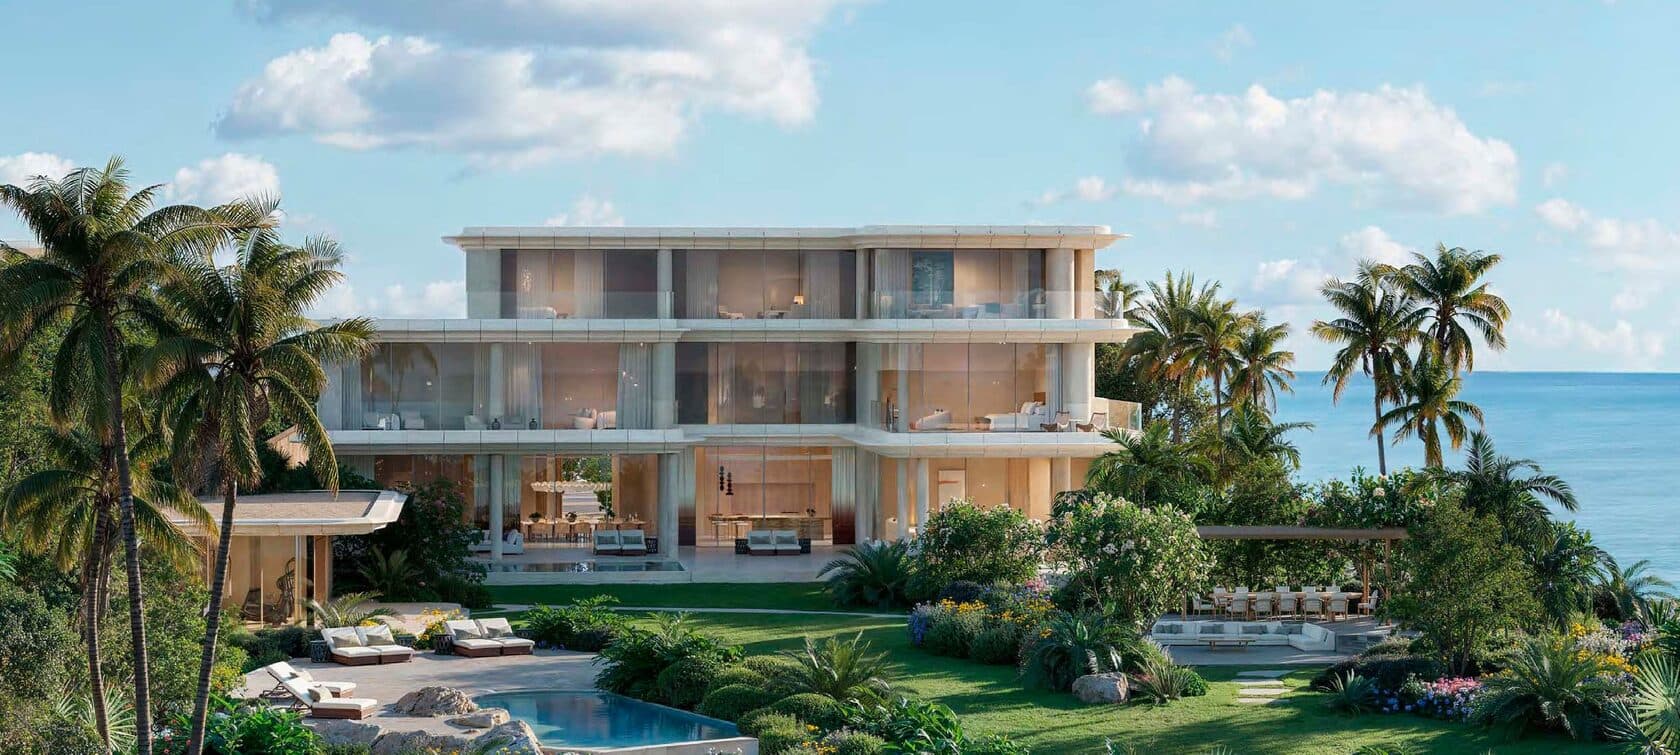
Meraas · Jumeirah
Meraas Ocean Mansions at Asora Bay, Jumeirah: four- to seven-bedroom beachfront homes from AED 65M, handover Q1 2029.
From
AED 65.00M
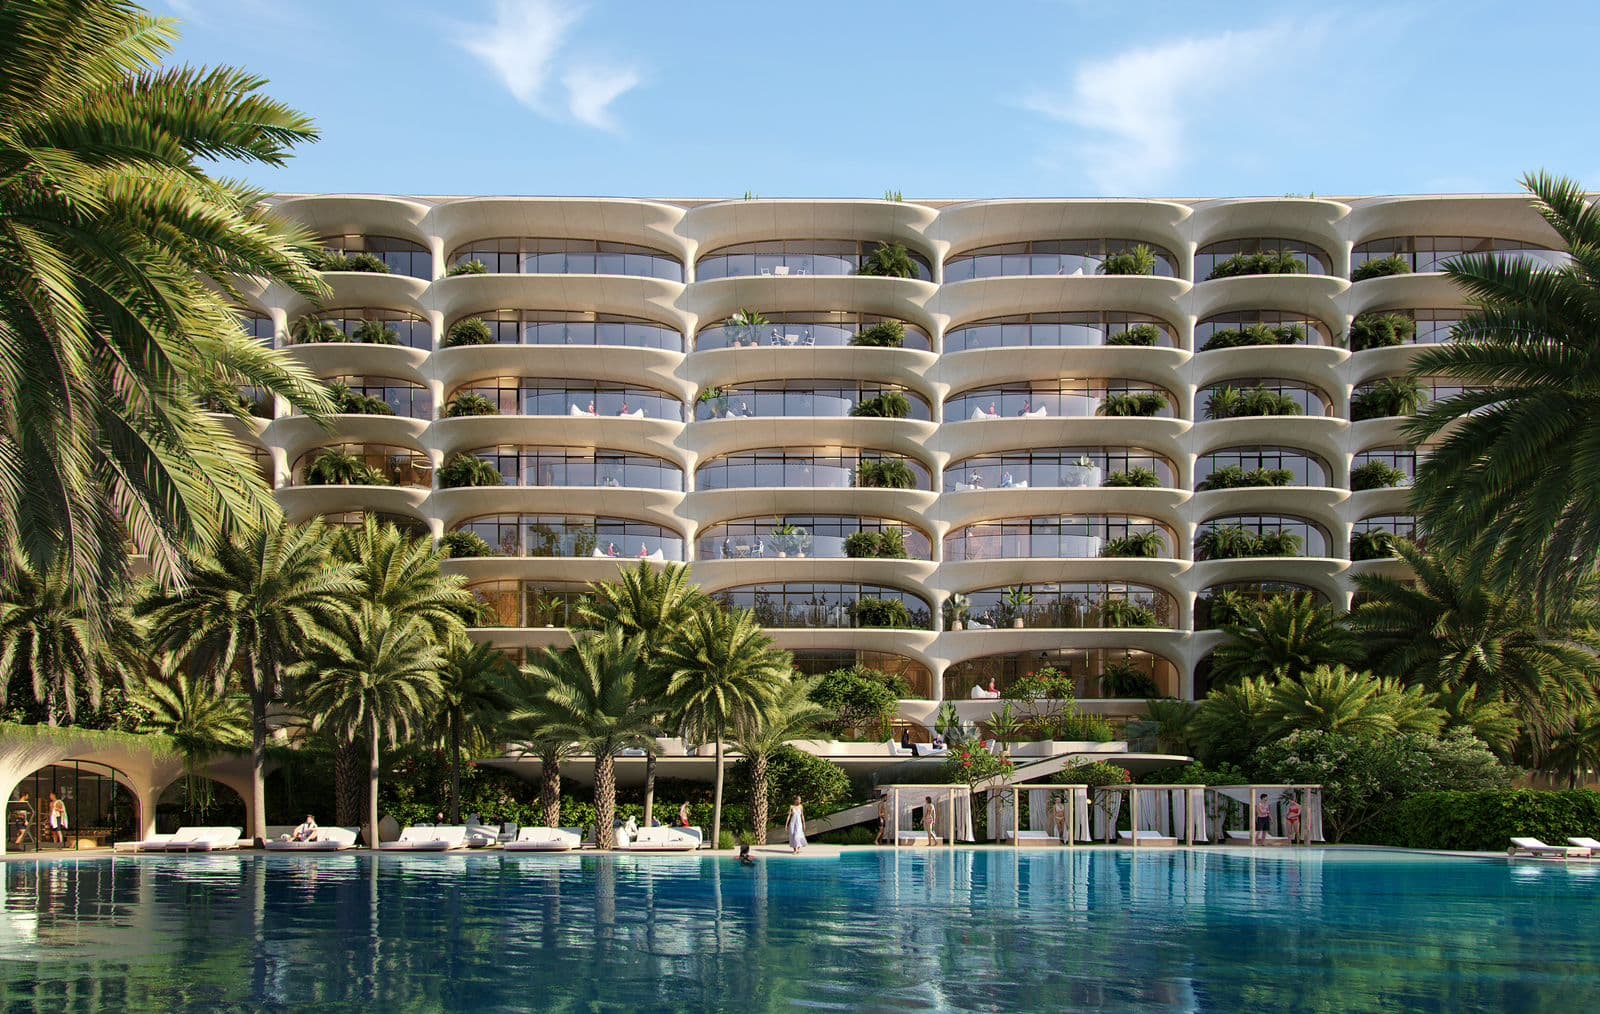
ELLINGTON · Palm Jumeirah
Ellington's Ocean House on Palm Jumeirah: two- to four-bedroom apartments sold off-plan from AED 22.58M, with spa and cinema.
From
AED 22.58M
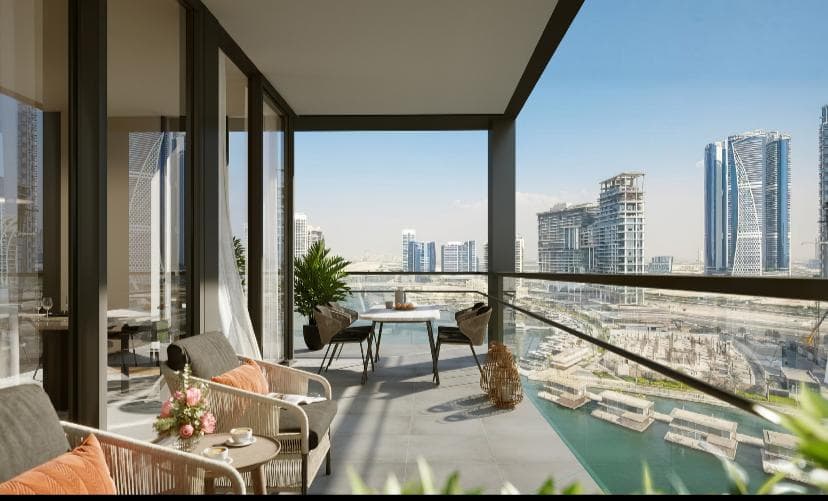
ELLINGTON · Business Bay
The Crestmark by Ellington in Business Bay: one- to four-bedroom apartments and penthouses off-plan from AED 2.97M, with four pools.
From
AED 2.97M
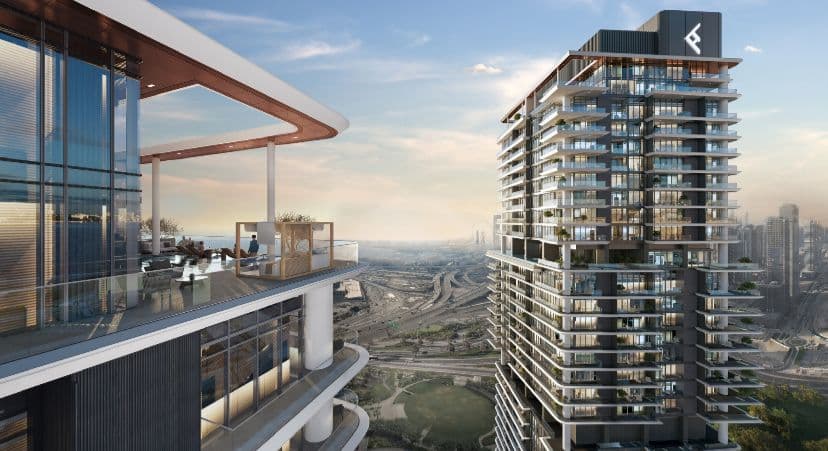
ELLINGTON · JLT
Mercer House by Ellington in JLT: studios to three-bedroom apartments from AED 3.73M, 70/30 plan, handover September 2027.
From
AED 3.73M
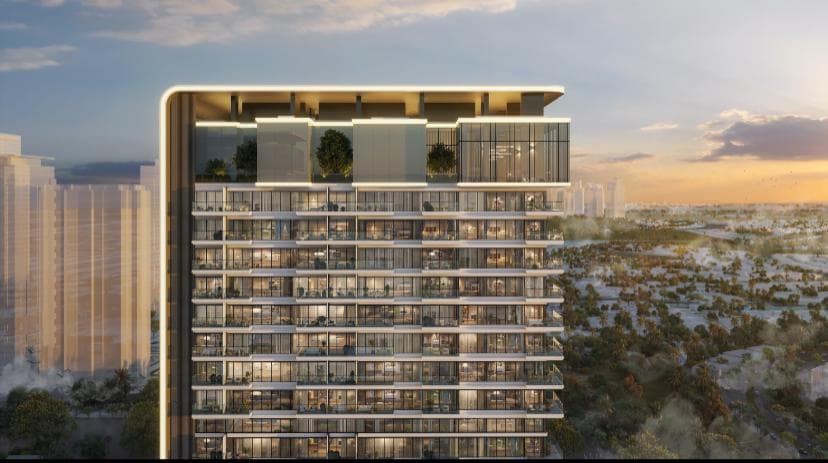
ELLINGTON · Jumeirah Lake Towers
Ellington Upper House in JLT: studios to three-bedroom apartments off-plan from AED 2.42M on a 70/30 plan, with padel court and skate park.
From
AED 2.42M
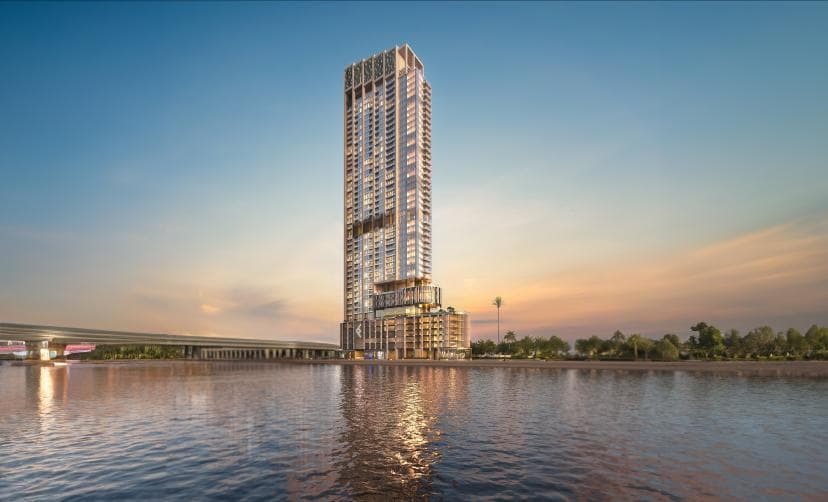
ELLINGTON · Business Bay
One River Point by Ellington in Business Bay: studios to three-bedroom apartments from AED 1.48M, handover December 2027.
From
AED 1.48M
FAQ
The questions our clients ask most often.
Yes. Several UAE banks — including Emirates NBD, ADCB, Mashreq, HSBC UAE and ADIB — offer mortgage products to non-resident foreign nationals. The loan-to-value limit is set by each bank rather than by the Central Bank, and is typically 50–60% of the property value, so plan for a 40–50% cash deposit. UAE residency is not a prerequisite for mortgage eligibility.
Typically 40–50% of the property value, because non-resident lending is each bank's own policy: ADIB, Mashreq and ADCB lend up to 50%, HSBC up to 60%. The Central Bank's 80% cap applies to resident expatriates on a first home up to AED 5M (70% above AED 5M, 60% for an investment property), and off-plan is 50% for everyone. On top of the deposit, budget for approximately 6–7% in transaction costs (DLD transfer fee of 4%, agency commission of ~2%, the registration trustee fee, mortgage registration fee of 0.25% of the loan amount, and the title deed fee).
Advertised rates in October 2026 start from about 4% per annum — ADCB from 3.99%, HSBC 4.05% fixed, ADIB non-resident finance from 3.99% — with Mashreq's representative one-year fixed rate at 5.00% and Emirates NBD pricing at one-month EIBOR + 1.99%. Most of these are resident rates, and non-resident pricing usually carries a premium. Variable rates now price off a higher EIBOR after the Central Bank raised its Base Rate to 3.90% on 17 September 2026, so expect a quote above the advertised resident rate. Fixed-rate periods of 1–5 years are common, after which the rate reverts to a variable rate linked to EIBOR. Comparing offers from multiple banks — or using a mortgage broker — will help you secure a competitive rate.
They are the same product under different names — "home loan", "mortgage" and "property finance" all describe a bank lending against the property. The only real distinction is conventional versus Islamic: conventional banks charge interest, while Islamic banks use Sharia-compliant structures such as Ijara or Murabaha and quote a profit rate instead. Both are open to non-residents of any faith, and the same bank LTV policies and DLD fees apply.
No. The Central Bank's Regulations Regarding Mortgage Loans set caps for UAE nationals and for resident expatriates (80% on a first home up to AED 5M, 70% above, 60% for a second or investment property, 50% for off-plan regardless of buyer) and have no non-resident category. Each bank sets its own non-resident limit: ADIB and Mashreq publish up to 50% of property value, HSBC up to 60%. Always ask a bank for its non-resident LTV specifically, because your real deposit is 40–50%, not the 20% a resident puts down.
The typical document pack includes a valid passport, last 6 months' bank statements showing income, a salary certificate or employment contract (for employees), or 2 years of audited accounts (for self-employed applicants), and details of the property to be purchased. Some banks also request a credit report from your home country. Applications can usually be initiated remotely.
Generally, UAE banks do not mortgage off-plan properties during the construction period. The mortgage is arranged at or near handover, once the property is complete and a title deed can be issued. During construction, the developer's payment plan serves as the financing mechanism. Some banks offer off-plan mortgage products with specific developers as exceptions, but these are not standard. If you plan to mortgage at handover, arrange pre-approval 6–12 months ahead of the expected completion date.
Our licensed advisors can guide you through every stage — from shortlisting properties to completing the DLD transfer.
We work with Dubai's leading developers


Get Started Today
Get a free consultation. We'll match you with the best properties for your goals and budget.